Does homeowners insurance cover a roof?
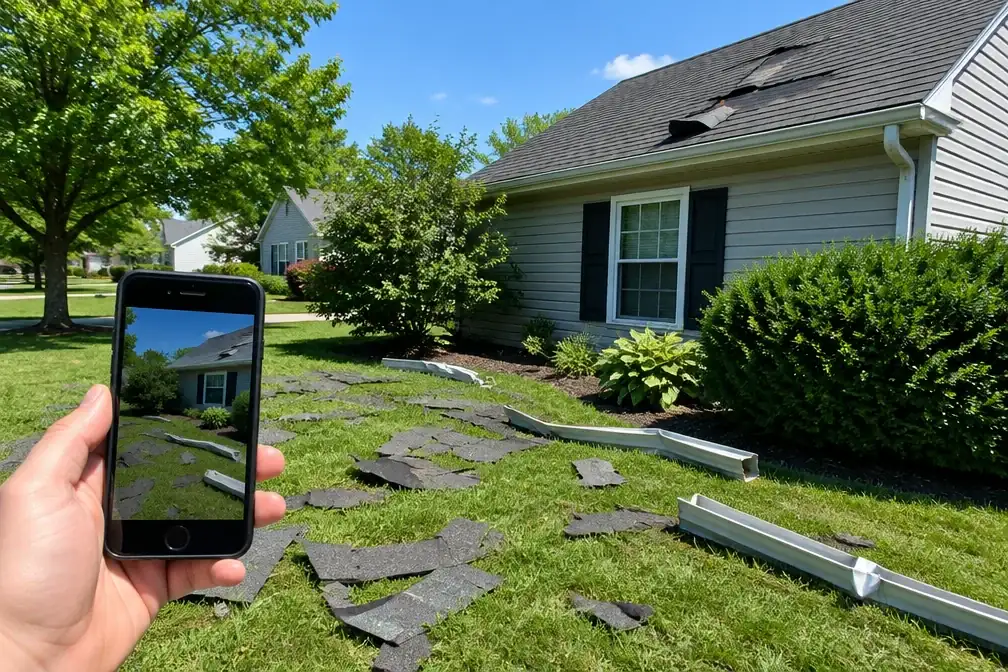
Sometimes. Insurance is meant for sudden damage, not old age. A roof torn up by wind or a fallen tree is often covered. A roof that simply wore out usually is not. Your policy and adjuster make the final call, but here is how it normally works and how to handle a claim well.
Updated
| Situation | Usually covered? |
|---|---|
| Wind tore shingles off in a storm | Often yes |
| Tree or limb fell on the roof | Often yes |
| Hail damage | Often yes |
| Fire damage | Often yes |
| Heavy snow or ice collapse | Often yes |
| Roof worn out from age | Usually no |
| Slow leak from bad flashing | Usually no |
| Poor installation | Usually no |
| Interior water damage from a covered event | Often yes |
What counts as storm damage on a roof
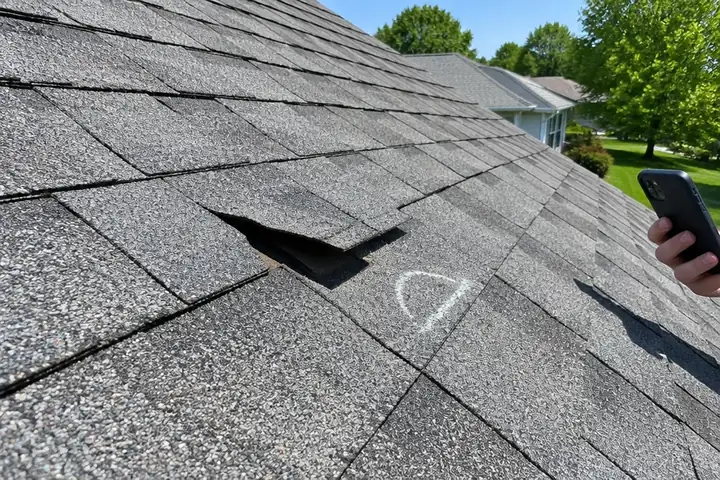
Adjusters look for damage from a specific event, as opposed to general wear. These are the signs they usually accept.
- Shingles missing, torn or creased across the upper third
- Lifted ridge caps and damaged rakes
- Bent or missing flashing and drip edge
- Round bruises or dents from hail, on shingles and soft metals
- Impact from limbs, with broken deck boards
- Dents on vents and gutters, on the same side of the house
Wind and hail in the Pittsburgh area
Wind is the main roof claim around here. Summer thunderstorms and strong winter fronts can lift shingles without blowing them off, and that creased shingle may look fine from the ground. Hail damage is less common, but it does happen, and it can be hard to see without getting on the roof. If a storm has been through your neighborhood, have the roof checked soon, because a claim gets harder as time passes.
How to handle a storm claim
- Prevent further damage. Tarp the roof and keep the receipt.
- Take dated photos of the roof, the yard and any inside damage.
- Call your insurance company as soon as you can.
- Get a roofer to inspect and put the damage in writing.
- Meet the adjuster on the roof, with your roofer if you like.
- Read the estimate, and ask questions before accepting it.
- Keep every receipt and letter.
Roof leak: should I call insurance?
First work out what caused it. If a storm or fallen limb opened the roof, call your insurer. If a leak came on slowly around old flashing, a claim is unlikely to succeed, and paying for a roof leak repair is probably the better route. The roof repair itself may not be covered, even when the ceiling damage is. Ask your agent about that before you file, since small claims can affect your premium.
Replacement cost or actual cash value
Check which one your policy uses for the roof. Replacement cost pays to put on a similar new roof, usually in two payments. Actual cash value takes off depreciation for age, so an old roof may pay out far less. Many policies now limit coverage on older roofs, so read yours before you need it.
| Example: $15,000 roof, 15 years old | Replacement cost | Actual cash value |
|---|---|---|
| Value after depreciation | $15,000 | About $7,500 |
| Your deductible | -$1,000 | -$1,000 |
| Paid to you | $14,000 | About $6,500 |
| You pay toward the roof | $1,000 | About $8,500 |
Deductibles and how you get paid
Your deductible comes out of any payment, and some policies have a separate wind or hail deductible set as a percentage of your home's insured value. On replacement cost policies, the first check usually covers the depreciated value. The rest, often called recoverable depreciation, comes after the work is done and you send in the final invoice. If you have a mortgage, the check may also name your lender, which can add a step before you can use it.
If your claim is denied or comes in low
A denial or low offer isn't always the last word. You can do the following.
- Ask for the reason in writing, and read that part of your policy.
- Ask for a reinspection, and have your roofer there with photos.
- Send a written scope showing what was missed.
- Hire a licensed public adjuster, who works for you for a share of the claim.
- Contact the Pennsylvania Insurance Department if you feel the claim was handled unfairly.
Is it worth filing a claim?
Compare the likely payment with your deductible. If a $1,500 repair sits under a $1,000 deductible, the $500 you might get may not be worth a claim on your record. For major damage, filing is what insurance is for. Your agent can usually tell you how a claim could affect your rate.
Our role in your claim
We inspect the roof, photograph what we find and give you a written scope and price. You work with your insurer on coverage. We don't negotiate your claim, and only you or a licensed public adjuster can do that. If the damage isn't a likely claim, we will tell you that as well.
If a storm has just hit, start with emergency roof repair. For pricing, see our asphalt roof cost guide.
Watch out for storm chasers
After a big storm, door-knockers often work through neighborhoods. Be wary of anyone who promises a free roof, offers to cover your deductible or asks you to sign before you have spoken to your insurer. Waiving a deductible isn't a favor, and it can create problems for you. Take your time, get a local phone number and check proof of insurance.
Common questions
Does homeowners insurance cover roof leaks?
A leak from sudden storm damage often is covered. A leak from wear, age or poor maintenance usually isn't, though resulting interior damage is sometimes treated differently.
Does homeowners insurance cover roof replacement due to age?
No, not normally. Age and wear are maintenance items. Some policies also reduce what they pay on older roofs even for storm damage.
Will insurance pay for a new roof?
If a covered event damaged it enough to need replacing, often yes, less your deductible. Partial damage may only pay for a repair.
Does homeowners insurance cover roof repair?
If a covered peril like wind, hail or a falling tree caused the damage, usually. Routine repairs from wear are on the homeowner.
Does homeowners insurance cover roof damage?
Sudden damage from storms, falling objects and fire usually is. Wear, neglect and old age usually aren't.
Does homeowners insurance cover roof leaks from rain?
Only if something covered, such as wind damage, opened the roof. Rain getting through a worn roof is usually not covered.
Can a roof leak be covered by insurance?
Yes, if a covered event caused it. Your adjuster decides, and photos of the damage help.
What does hail damage look like on a roof?
Round bruises in the shingles, loss of granules in spots and dents on soft metal such as vents and gutters.
Does a new roof lower home insurance?
Often a little, and it can keep you eligible for better coverage. Tell your agent when the roof is replaced.
Does a new roof come with a warranty?
Usually two: the manufacturer's warranty on the materials and the contractor's workmanship warranty. Get both in writing.
More roofing services
- repairs from our Pittsburgh roofers
- new roofs from our roofers
- help with roof leaks
- emergency roofers
- slate roofers in Pittsburgh
- rowhouse rubber roofs
- metal roofing in Pittsburgh
- small commercial roofs
- seamless gutters in Pittsburgh
- soffit and fascia work
- roof inspection in Pittsburgh
- ice dam removal
- roof ventilation